If the IRS has warned you that it may prepare a Substitute for Return, file the missing return and respond to the notice before the deadline printed on it. If the IRS has already processed the SFR, you can generally still submit your own accurate return so the IRS can adjust your account to reflect what you actually owe.
| Key takeawaysThe IRS can prepare a return for you if you don’t file one, using only income data from employers and banks.An SFR skips deductions, credits, and dependents, so the tax bill it produces is almost always higher than the real amount.A CP3219N notice gives you 90 days (150 days if you live outside the U.S.) to petition Tax Court, and filing a late return does not extend that clock.Filing your own return after an SFR generally qualifies you for audit reconsideration under IRS procedures.Collection action, including a federal tax lien or wage levy, typically follows an unpaid SFR assessment. |
What Is an IRS Substitute for Return (SFR)?
A Substitute for Return is a tax return the IRS prepares on your behalf when you don’t file one yourself.
- The IRS builds it using W-2s, 1099s, and other third-party income records it already has on file.
- It does not include your deductions, exemptions, dependents, or business expenses, because the IRS has no way to know about them unless you report them.
- The result is a tax bill that can be two to three times higher than what a correctly filed return would show.
Why You Should Act Before the IRS Files an SFR
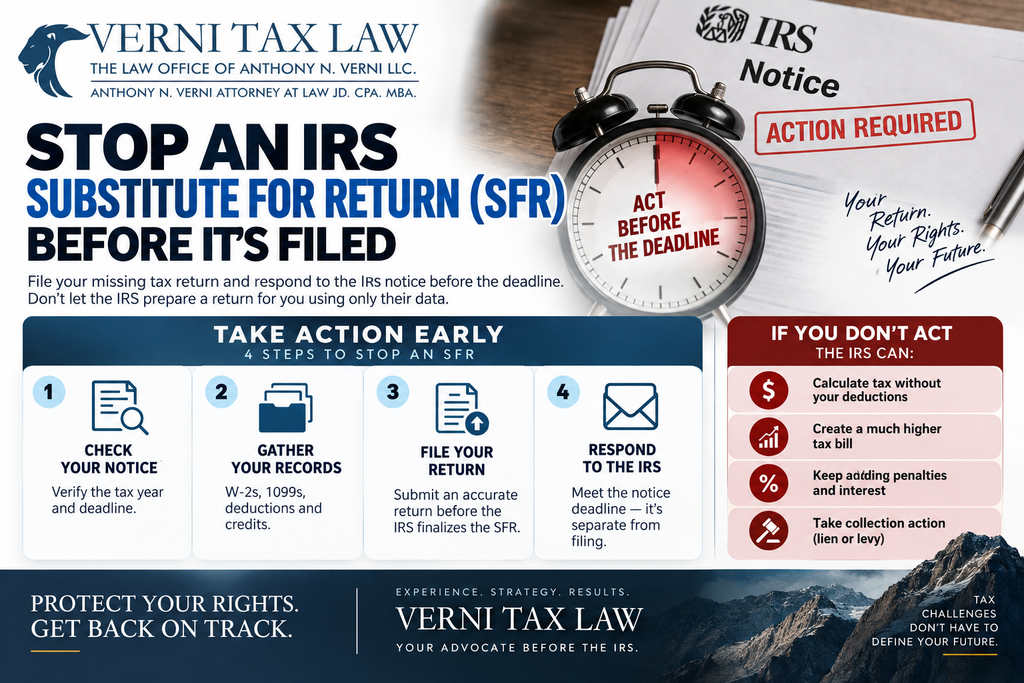
Acting before the IRS finalizes an SFR protects your deductions, your filing status, and your wallet from an inflated assessment. Waiting costs you on four fronts:
- The IRS calculates tax without your deductions. No mortgage interest, no dependents, no business write-offs, no retirement contributions.
- An SFR often creates a larger tax assessment than your real liability, sometimes dramatically so.
- Penalties and interest keep accumulating on the inflated balance, not on what you’d actually owe.
- Collection actions can follow once the assessment is final, including liens and levies against wages or bank accounts.
Can You Stop an IRS Substitute for Return Before the IRS Prepares It?
Yes, in most cases you can still stop SFR IRS action by filing your own return before the agency finalizes its version.
If the SFR Has Not Yet Been Processed
You file the required return and respond to whatever notice you received before its deadline. This is the cheapest, fastest way to stop the IRS from substituting your return before it locks in a number you’ll spend months disputing later.
If the IRS Has Already Prepared or Processed the SFR
You file your own accurate return and let the IRS adjust the resulting assessment. The IRS states directly that taxpayers should file their own return even after an SFR, because the IRS-created version may not include all applicable deductions and credits you’re entitled to claim.
The IRS Notice Matters More Than the Phrase “SFR”
The table below shows a progression: earlier letters are warnings you can still act on, while a CP3219N means the clock on your appeal rights is already running.
Here’s how the notices differ in what they actually mean:
| Notice | What it signals |
| CP59 | First notice that the IRS has no record of your return |
| CP515 / CP516 / CP518 | Reminder and final-reminder notices, no SFR filed yet |
| CP2566 | The IRS calculated tax based on income data after prior notices went unanswered |
| CP3219N | Notice of Deficiency (90-day letter), the SFR has been proposed as an assessment |
What Should You Do If You Have Multiple Unfiled Tax Returns?
Filing the oldest year first is not always correct if you have multiple unfiled tax returns. Start by pulling your IRS wage and income transcripts for every open year, since that tells you which years actually have income data the IRS will use against you.
- Request transcripts through your IRS Online Account or Form 4506-T for each missing year.
- Prioritize any year with a notice deadline attached. That year controls your timeline.
- Reconstruct income and deductions using bank records, pay stubs, and prior returns as templates.
- File the returns in a batch when possible, since the IRS Automated Substitute for Return unit processes related years together.
- Track the IRS statute of limitations on unfiled tax returns carefully. There is no deadline that stops the IRS from assessing an unfiled year, but a refund claimed on a return filed more than three years late is lost for good.
What Should You Do Immediately If the IRS Has Not Filed the SFR Yet?
Move on four fronts at once rather than treating this as a single task.
Step 1: Identify the Missing Tax Year and Exact IRS Deadline
Verify the tax year, your name as shown on the notice, the notice number, the notice date, the response deadline, the income the IRS lists, and the phone number printed on the letter.
Step 2: Reconstruct the Missing Tax Return Before Responding
Gather W-2s, 1099s, 1098s, brokerage and investment statements, business income records, deductible expense receipts, your prior-year return, and proof of any estimated tax payments. Compare the income the IRS lists against your own records.
If a W-2 or 1099 amount looks wrong, you should contact the payer directly for a corrected form before filing.
Step 3: File the Actual Return Instead of Waiting for the SFR
Your own accurate return is the central corrective action here. Include every deduction and credit you legitimately qualify for. An IRS-generated return has no way to know about them.
Step 4: Respond to the IRS Notice Separately When Required
Filing the return and meeting the notice deadline are two different obligations. This distinction matters most once a CP3219N has been issued, since the IRS accepts your late return but still holds you to the separate 90-day petition window.
Why Filing Your Own Return Is Usually Better Than an SFR
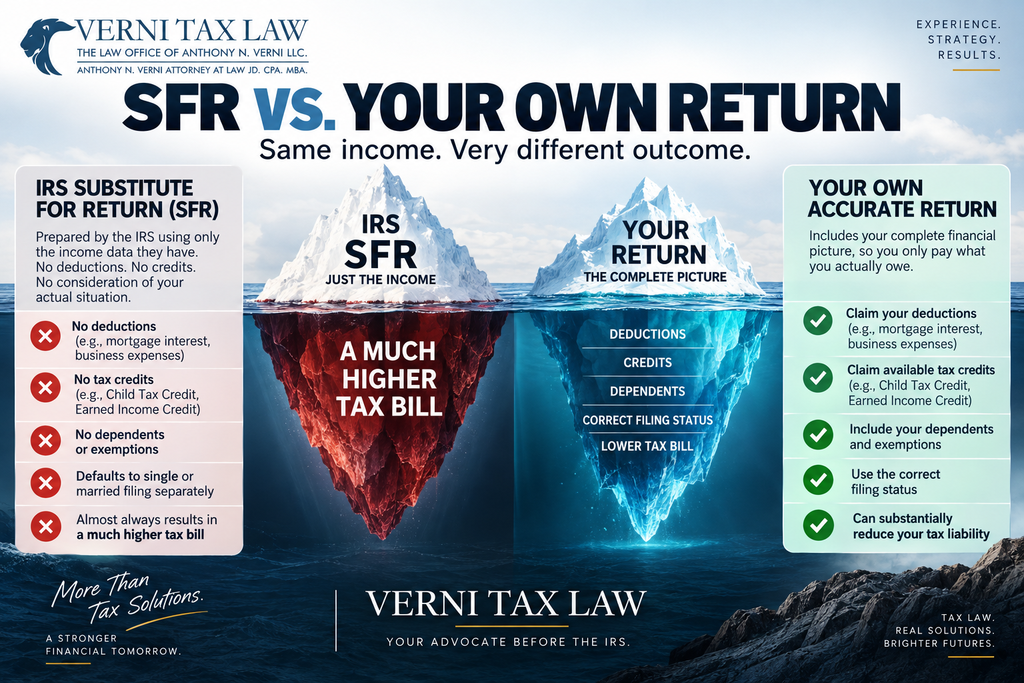
The advantages of filing your own return, rather than letting an SFR stand, include:
- Claiming deductions you actually qualify for, from mortgage interest to business expenses
- Claiming available tax credits, including the Child Tax Credit and Earned Income Tax Credit where eligible
- Correcting IRS income information that came from a wrong or outdated third-party form
- Reducing the resulting tax liability, often substantially, once accurate numbers replace the IRS estimate
- Restoring your filing status, since an SFR defaults to single or married filing separately regardless of your actual status
What Happens If the IRS Has Already Prepared an SFR?
An SFR does not end your opportunity to file your own return. You can still file after an SFR and that it will generally adjust the account to reflect the correct figures once it processes your return.
- Obtain your IRS notice or account transcript, and determine exactly what income the IRS included.
- Prepare your actual return, including every deduction and credit you’re entitled to.
- File the delinquent return through the method that applies to that tax year, keep proof of filing and every supporting document, and monitor your IRS account until the adjustment posts.
What Is a CP3219N 90-Day Letter, and Why Is It the Critical SFR Deadline?
A CP3219N is a Notice of Deficiency, commonly called a 90-day letter. You generally have 90 days from the notice date to petition the U.S. Tax Court, or 150 days if the you are outside the United States.
If You Disagree With the Proposed IRS Tax
You can file the past-due return to correct the numbers, or you can petition Tax Court if you’re challenging the deficiency itself. Filing the late return does not extend the Tax Court petition deadline. The 90-day (or 150-day) window keeps running regardless of what else you file.
Why You Should Not Treat the 90-Day Deadline Like an Ordinary Filing Extension
Once a CP3219N arrives, you’re tracking two separate clocks. One governs how long the IRS needs to process your late return. The other is a hard statutory deadline for going to Tax Court. Missing the second one because you assumed filing the return was enough is a common, costly mistake.
Can You Request Audit Reconsideration After an IRS SFR?
Yes. IRS procedures recognize audit reconsideration as a way to dispute IRS-filed return determinations, including ones created through the SFR process. Audit reconsideration applies when you contest an SFR determination by filing an original delinquent return.
The IRS generally grants reconsideration when:
- You’ve filed a tax return covering the disputed period
- The assessment remains unpaid, or specific credits were denied
- You can identify exactly which adjustments you’re disputing
- You have new information the IRS didn’t previously consider, or the IRS made a computational or processing error
An SFR does not necessarily end the dispute. Filing the correct original return can reopen the assessment for reconsideration.
How an SFR Can Lead to IRS Collection Actions
An unpaid SFR assessment becomes a tax bill, and an unpaid tax bill triggers collection. That can include:
- A federal tax lien filed against your property
- A levy on wages or bank accounts
- Offset of future refunds against the balance
- Additional penalties, or in repeated cases, referral for further enforcement
Your Tax Debt Resolution Options
Several IRS debt settlement options exist once a balance is confirmed.
- An IRS installment agreement spreads payments over time.
- A partial-pay installment agreement works when you can’t cover the full balance even over an extended term.
- An Offer in Compromise for back taxes and unfiled returns allows qualifying taxpayers to settle for less than the full amount owed.
If federal tax liens and levies are already in place, specific procedures can remove an IRS tax lien or release a levy once you’re in compliance or under an approved agreement.
When Should You Contact an IRS Substitute for Return Attorney?
Bring in an IRS substitute for a return attorney when the following situations are involved:
- You’ve received a CP3219N and the 90-day window is already running
- Multiple years are unfiled, and the IRS has opened a delinquency investigation
- A lien or levy has already been filed against your wages, accounts, or property
- Self-employment or business income makes reconstructing the return complicated
- You’re weighing a Tax Court petition against filing a late return
- The IRS denied a prior attempt at reconsideration or resolution
How Verni Tax Law’s IRS Tax Attorney Can Help Stop or Correct an SFR
Anthony N. Verni is a tax attorney and CPA with an MBA and over 20 years of experience practicing before the IRS, and he’s the right choice when an SFR is threatening to lock in a number you don’t actually owe.
He personally handles every case, which matters when a 90-day Tax Court deadline is running against you. Here’s exactly how he helps:
- He reviews your IRS transcripts and notices to identify precisely which tax years and income figures are in dispute.
- He prepares and files the accurate return needed to replace an IRS-filed return and pursues audit reconsideration where you qualify.
- He represents you directly before the IRS, so you’re never explaining your case to an agent alone.
- He evaluates whether a Tax Court petition, an installment agreement, or an Offer in Compromise fits your specific numbers.
- If a lien or levy has already hit, he moves to pause collection while the corrected return is processed.
If you need help with an unfiled tax return, a tax attorney for back taxes, or are already facing civil tax litigation tied to a disputed SFR, book a consultation with Verni Tax Law before your deadline passes.
Conclusion
An SFR is a placeholder built from partial information, and your own accurate return generally replaces it once filed. The deadline that actually matters is the one printed on your notice, particularly if it’s a CP3219N, because that 90-day window doesn’t pause for a late return in progress.
Filing your own return, checking every income figure the IRS used, and pursuing audit reconsideration where warranted are the concrete steps that turn an inflated assessment into an accurate one.
Anthony N. Verni brings both a law license and a CPA credential to exactly this kind of dispute, which means the tax math and the legal deadlines get handled by the same person instead of two separate professionals working from different files. His clients get direct representation before the IRS from the first notice through the final adjustment.
Don’t wait for the 90-day clock to run out on its own. Contact Verni Tax Law today for a confidential consultation.
FAQs
What is an IRS Substitute for Return?
It’s a tax return the IRS prepares for you when you don’t file one, using only third-party income data with no deductions or credits applied.
Can I stop an IRS Substitute for Return before it is filed?
Yes. Filing your own accurate return before the IRS finalizes the SFR generally prevents it from being processed.
Why would the IRS file a substitute return for me?
The IRS files an SFR when it has income records showing you should have filed but has no return on file for that year.
How does the IRS notify me before filing an SFR?
Through a series of notices, typically CP59, then CP515 or CP516, then CP518, before a CP3219N proposes the actual assessment.
What happens if I ignore an IRS SFR notice?
The IRS proceeds with its proposed assessment, and unpaid balances move into collection, including liens and levies.
Is it better to file my own tax return than let the IRS prepare an SFR?
Yes. Your own return includes deductions, credits, and the correct filing status, which almost always lowers the total tax owed.
Can filing my own return reduce an IRS SFR tax assessment?
Yes, substantially in most cases, since the SFR excludes exemptions and deductions your own return would claim.
What if the IRS has already filed a Substitute for Return?
You can still file your own accurate return, and the IRS will generally adjust your account to the correct figures.
Can I dispute an IRS-filed return?
Yes, through audit reconsideration, by filing an original delinquent return that the IRS then reviews against the SFR assessment.
Can I request SFR reconsideration after the IRS files a return?
Yes, provided you file a return, the balance is unpaid, or credits were denied, and you present new or corrected information.
What happens to penalties and interest after an SFR?
They continue accruing on the assessed balance until you file your own return or otherwise resolve the account.
Can an SFR lead to a tax lien or bank levy?
Yes. An unpaid SFR assessment becomes collectible, and the IRS can file a lien or issue a levy once the balance is final.
Can an IRS Substitute for Return attorney help me?
Yes. An IRS tax attorney can file the corrective return, pursue reconsideration, and represent you directly if a Tax Court deadline applies.