Moving your laptop to another country does not just change your view. It can trigger two separate federal reporting duties: FBAR for remote workers and foreign payroll account reporting.
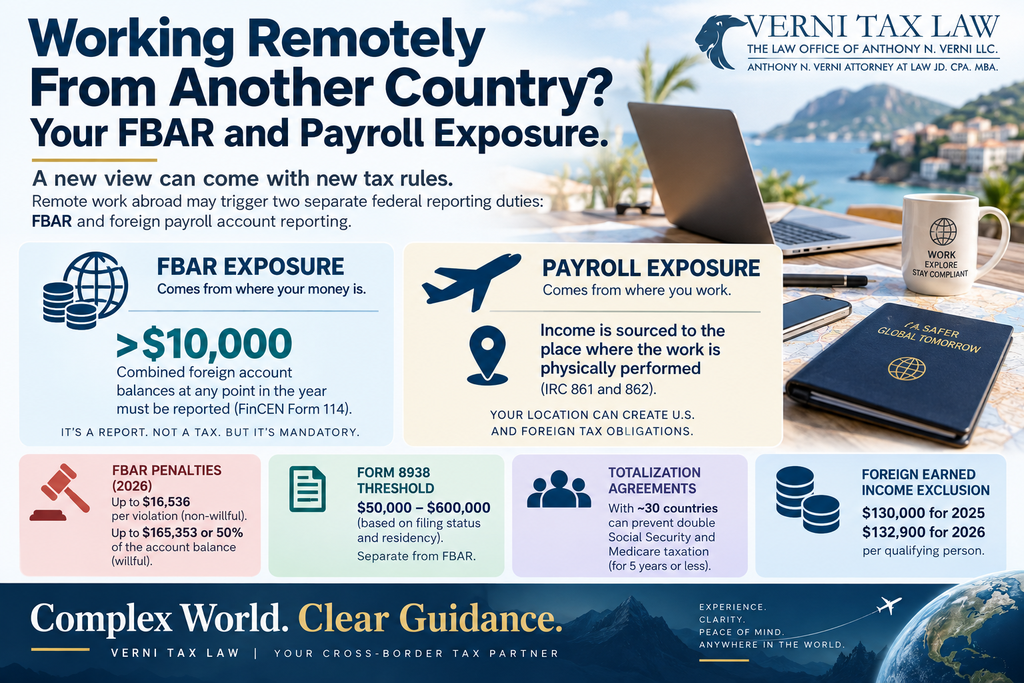
FBAR exposure comes from where your money is. Payroll exposure comes from where you physically work. This guide breaks down when each rule applies, what the IRS and FinCEN actually require, and what to do if you already fell behind.
Key takeaways
- A foreign account tied to remote work foreign account tax rules must be reported once your combined foreign balances exceed $10,000 at any point in the year, per IRS and FinCEN guidance.
- FBAR (FinCEN Form 114) and Form 8938 are separate filings with different thresholds. IRS guidance confirms Form 8938 does not replace FBAR.
- Personal service income is sourced to where the work is physically performed.
- The 2026 non-willful FBAR penalty can reach $16,536 per violation; willful penalties can reach the greater of $165,353 or 50% of the account balance.
- Totalization Agreements with roughly 30 countries can prevent double Social Security and Medicare taxation for employees sent abroad for five years or less.
- The Foreign Earned Income Exclusion is $130,000 for 2025 and $132,900 for 2026 per qualifying person.
Does Working Remotely Abroad Create U.S. Tax Obligations?
Yes. The United States taxes citizens and green card holders on worldwide income, regardless of where they are physically while earning it.
- U.S. citizens working remotely for U.S. companies still file a full US return every year, wherever they live. Foreign taxes paid may reduce that bill through a credit, but the filing obligation should never be ignored.
- Non-U.S. citizens working remotely for U.S. companies face a different test. A nonresident alien is generally taxed only on US-source income, and personal service income is sourced to where the work happens.
What Is FBAR and Why Could It Apply to Remote Workers?
FBAR for remote workers applies once you qualify as a US person and holds US person status, a financial interest in or signature authority over a foreign account, and an aggregate account value above $10,000 at any point in the year.
- An FBAR is a report, a mandatory annual disclosure of foreign financial accounts filed with FinCEN, separate from a tax return.
- It does not create new tax; it creates a reporting duty.
| A US employee working for a US employer gets paid into a foreign bank account, and that account’s balance crosses $10,000 at some point during the year. The source of the salary and the location of the employer do not decide whether the account is reportable. Only the account’s foreign location and its peak balance matter for FBAR filing requirements. |
The aggregate rule: If you hold four foreign accounts worth $3,000 each, the individual balances look harmless, but the combined total of $12,000 still triggers the filing requirement.
Which Foreign Accounts Can Put a Remote Worker Into FBAR Territory?
Any of these, once the aggregate crosses $10,000:
- Checking accounts
- Savings accounts
- Brokerage and securities accounts
- Certain mutual fund and pooled investment accounts
- Joint accounts, including those held with a non-US spouse
- Accounts where you have signature or other authority but no ownership
- Accounts at foreign branches of banks headquartered anywhere, including US banks
Receiving your salary through an account is not the trigger. The account’s status as a qualifying foreign financial account and its balance against the $10,000 threshold decide the outcome.
Form 8938 reporting requirements are required at much higher thresholds ($50,000 to $600,000, depending on filing status and residency), and the form is filed with the IRS as part of your tax return.
The table below shows how the two forms differ in practice.
| Feature | FBAR (FinCEN Form 114) | Form 8938 |
| Filed with | FinCEN, separate from your return | IRS, attached to Form 1040 |
| Threshold | $10,000 aggregate, any US person | $50,000 to $600,000, based on status and residency |
| Covers | Bank, brokerage, and similar accounts | Broader asset types, including some foreign stock and interests |
| Penalty for missing it | Up to $16,536 non-willful, higher if willful | Up to $10,000, rising to $50,000 for continued failure |
Foreign Payroll Accounts: What Remote Employees Need to Know
Depositing your salary into a foreign account does not change your income tax obligations, but it does put that account on the FBAR radar once the balance clears $10,000. Treat the account like any other foreign account from day one.
Employer Payroll Accounts vs. Your Personal Account
A US employer’s own payroll processing account overseas is the employer’s compliance problem. Your personal foreign account, the one receiving your paycheck, is yours to track and report.
Independent Contractors and Foreign Business Accounts
Contractors who open a foreign business account to receive client payments face the same $10,000 aggregate test as employees. A business structure does not exempt a US person from personal FBAR duties if they hold a financial interest in the account.
What Foreign Assets May Need to Be Reported?
- Foreign bank and savings accounts, once combined balances exceed $10,000
- Foreign investment and brokerage accounts holding stock, funds, or securities
- Foreign pension and retirement accounts, which often surprise filers because they assume domestic-style tax deferral applies
- Foreign digital asset and crypto accounts held through a foreign exchange, which FinCEN treats similarly to other foreign financial accounts
Does Working Abroad Change Your Tax Residency?
- U.S. Tax Residency and Worldwide Income: Citizenship-based taxation means worldwide income stays reportable on a US return no matter how long someone lives overseas.
- Foreign Tax Residency Rules: Most countries use their own physical-presence or domicile tests, commonly a 183-day rule, to decide who owes local tax. A remote worker can become a tax resident in the host country while remaining a US taxpayer at the same time.
- Tax Treaties and Residency Conflicts: Tax treaties include tie-breaker rules for people who qualify as residents of both countries at once. These provisions do not cancel FBAR or FATCA duties, which sit outside income tax treaties entirely.
Can You Be Taxed in Both Countries?
Often, yes, but relief exists.
- Foreign Tax Credit: The Foreign Tax Credit lets a US taxpayer offset US tax with income tax already paid to a foreign government, dollar for dollar up to certain limits, using Form 1116.
- Foreign Earned Income Exclusion: The Foreign Earned Income Exclusion lets qualifying taxpayers exclude foreign wages from US taxable income entirely, up to $130,000 for 2025 and $132,900 for 2026 per qualifying person.
- Qualification requires passing either the bona fide residence test or the physical presence test.
A treaty can reduce or eliminate double taxation on specific income categories, but treaty benefits vary by country and often require a separate election on the return. Solid U.S. expat tax advice at this stage prevents claiming a benefit that does not apply to your specific facts.
What Payroll Issues Can Arise When You Work From Another Country?
A US employer generally keeps withholding federal payroll taxes unless a specific exception applies, even while the employee works abroad.
Foreign Employer and U.S. Tax Reporting
A foreign employer has no US withholding duty, which shifts the burden onto the employee to handle estimated payments and filing U.S. taxes from overseas correctly.
Social Security and Medicare Considerations
Totalization agreements between the US and roughly 30 countries prevent paying Social Security and Medicare tax twice on the same wages. Under the standard rule, an employee sent abroad for five years or less by the same US employer typically stays covered by US Social Security and stays exempt from the host country’s equivalent tax.
Contractor vs. Employee Classification
Misclassifying a remote worker as a contractor changes who owes self-employment tax and who handles Totalization Agreement paperwork. Getting this wrong creates back-tax exposure for both sides.
Workation Tax Risk: Does Temporary Remote Work Abroad Count?
Yes, even a short trip carries workation tax risk. Some countries start counting local tax residency or trigger permanent establishment concerns after as little as 90 days of remote work performed from within their borders.
Digital Nomad Tax Exposure
A US citizen bouncing between countries on a laptop remains fully subject to US filing rules the entire time, and each host country applies its own separate residency threshold.
Working From Multiple Countries in One Year
Splitting a year across three or four countries can mean partial-year tax residency claims in more than one place, plus a US return covering the full year regardless of the split.
When a Temporary Stay Can Create Local Tax Exposure
A stay long enough to trigger local tax residency, commonly 183 days, can create a local filing duty even for someone who never intended to relocate permanently.
What Should You Do If You Never Reported a Foreign Account?
- Confirm which years the aggregate balance crossed $10,000, going back as far as records allow.
- Determine whether the missed income was fully reported and taxed on your US returns.
- If income was reported correctly but the FBAR itself was missed, delinquent FBAR submission procedures may apply, since the IRS states it generally will not assess a penalty when tax on the related income was already paid and the taxpayer has not been contacted about an examination.
- If income was not reported, streamlined FBAR filing through the Streamlined Filing Compliance Procedures is usually the stronger path, requiring three years of amended or delinquent returns plus six years of FBARs.
- Confirm eligibility for the Streamlined Foreign Offshore track, which carries a 0% penalty for taxpayers who lived outside the US for at least 330 days in one of the relevant years.
- Get a written non-willfulness certification prepared correctly before submitting anything, since a wrong certification can escalate a fixable problem into an audit.
Remote Work Abroad: A Compliance Checklist
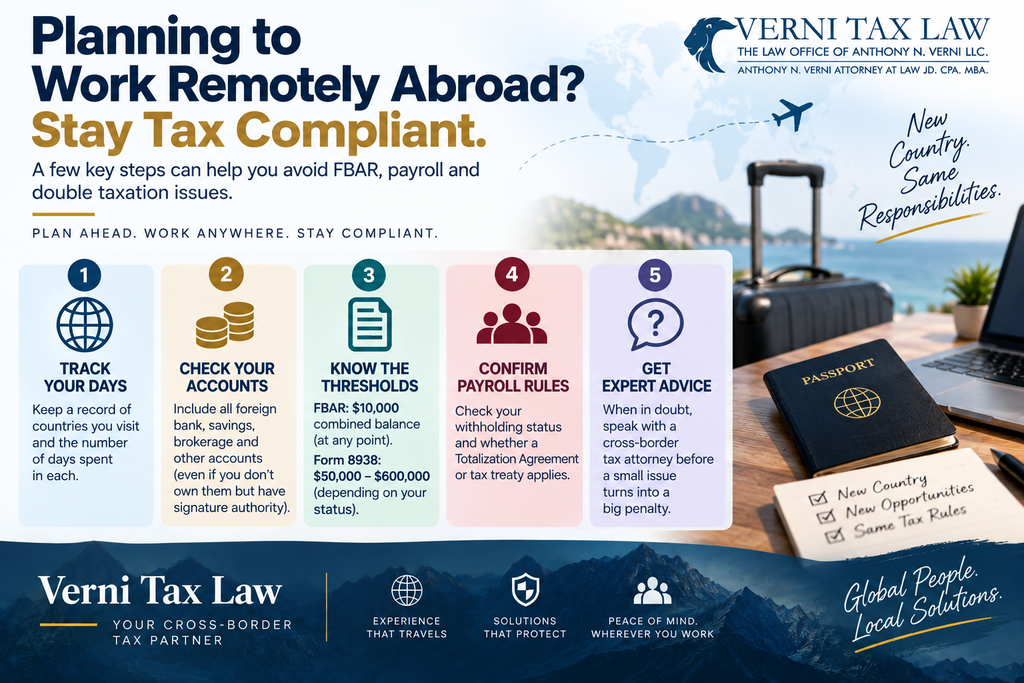
Track every country and the number of days spent there, since source-of-income and residency rules both hinge on physical location.
- Include salary accounts, savings, brokerage, and any account where you hold signature authority, even without ownership.
- Check the highest balance each account reached at any point, not the year-end balance, since FBAR uses a peak-value test.
- Compare your totals against both the $10,000 FBAR threshold and the higher Form 8938 thresholds for your filing status and residency.
- Confirm withholding status with your employer and check whether a Totalization Agreement or tax treaty changes what you owe.
How Verni Tax Law’s Cross-Border Remote Work Tax Attorney Can Help
Remote work tax problems rarely stay small. A missed FBAR, an unreported foreign account, or a misclassified payroll arrangement can compound into years of exposure before anyone notices.
Anthony N. Verni is a cross-border remote work tax attorney who also holds CPA and MBA credentials, giving him a combined legal and financial view of cases involving remote work foreign account tax questions, foreign payroll accounts, and multi-country residency conflicts.
He has represented clients through the Offshore Voluntary Disclosure Program since 2009 and has secured waived FBAR penalties for clients who inadvertently failed to report foreign accounts.
As an FBAR tax attorney, he can:
- Review your specific accounts, work location history, and payroll structure to determine exactly which filings apply to your situation
- Prepare filings for expat taxes through Streamlined Filing or delinquent FBAR procedures, whichever fits your facts
- Pursue FBAR penalty mitigation if the IRS has already proposed a penalty on unreported accounts
- Handle communication with the IRS directly, so you are not explaining a foreign payroll setup to an examiner alone
If you moved abroad, opened a foreign account, or started splitting your year across countries and are unsure what you owe, book a confidential consultation with Verni Tax Law before a small gap turns into a penalty notice.
Conclusion
FBAR for remote workers and foreign payroll account reporting are two separate legal tests, one triggered by account balances, the other by physical work location, and both apply regardless of where your employer is based.
The $10,000 FBAR threshold, the Form 8938 thresholds, and the source-of-income rules under IRC 861 and 862 each answer a different question, and confusing them is the most common way remote workers fall out of compliance without realizing it.
Anthony N. Verni brings 25 years of combined legal and CPA experience to exactly this kind of cross-border case. He personally reviews every file, from a single overlooked foreign account to a multi-year delinquent U.S. tax returns for expats situation, and builds a filing strategy around your actual facts rather than a generic checklist.
Contact Verni Tax Law today for a confidential review of your foreign accounts and payroll setup before the IRS or FinCEN sends the first notice.