IRS-CI now plays a major role in cases involving hidden crypto income, false returns, money laundering, and related financial crimes. IRS crypto enforcement combines tax, exchange, blockchain, and criminal evidence.
IRS guidance treats digital assets as property, while Form 1099-DA has expanded broker reporting. In 2026, brokers report gross proceeds and certain basis information. This article explains investigations, reporting rules, and response options.
Key Takeaways
- 2014: Notice 2014-21 treated virtual currency as property for tax purposes.
- 2025: Brokers began reporting gross proceeds on Form 1099-DA.
- 2026: Basis reporting applies to certain covered digital assets.
- 75%: The civil fraud penalty can apply to fraudulent underpayments.
- 5 years: Tax evasion under §7201 can carry this maximum prison term.
Why Cryptocurrency Has Become an IRS Enforcement Priority
Cryptocurrency is an IRS enforcement priority because taxable activity can move across wallets, exchanges, and borders. Third-party reporting now gives investigators more data. Those records can be compared with returns.
- IRS enforcement of digital assets includes tax reporting and related financial crimes.
- Taxable income remains reportable without Form 1099-DA.
- Basis reporting applies to certain covered securities after January 1, 2026.
- IRS-CI reported more than $3.5 billion in crypto seizures in FY2021.
- Ahlgren received two years in prison and $1,095,031 in restitution.
Expansion of IRS-CI’s Crypto Enforcement Efforts
IRS-CI moved from early cyber cases into broader financial investigations. Its Cyber Crimes program began with one Washington, D.C., unit in 2014, then added a Los Angeles unit and national support.
What Is IRS Criminal Investigation (IRS-CI)?
IRS-CI is the IRS law enforcement arm for criminal tax violations and related financial crimes. An IRS cryptocurrency investigation can move beyond a civil review. That shift matters when evidence suggests willfulness.
Special agents investigate tax fraud and money laundering. CI has investigative jurisdiction over Internal Revenue Code violations.
How IRS-CI Works with the DOJ Tax Division
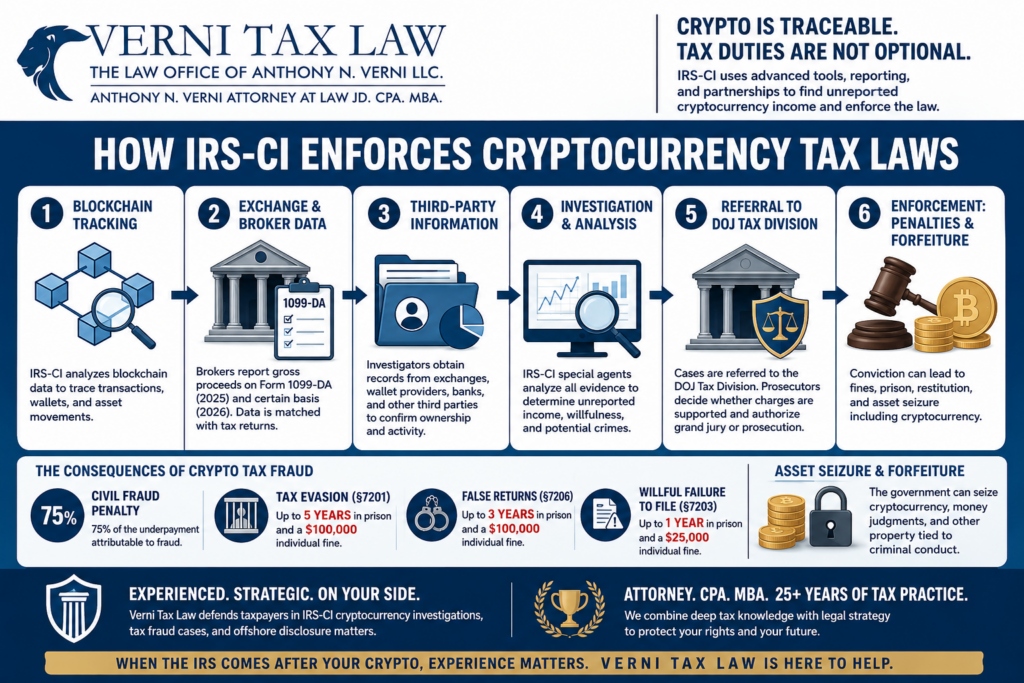
The DOJ Tax Division handles or supervises most federal criminal tax prosecutions. IRS-CI gathers evidence and refers matters for review.
DOJ prosecutors may authorize grand jury investigations or prosecutions. That process shapes the DOJ crypto enforcement strategy in tax cases, while prosecutors decide whether charges are supported.
Evolution of IRS Cryptocurrency Enforcement
IRS crypto enforcement moved from property rules to broker reporting and specialized investigations, shifting investigators’ data and creating more comparison points.
Early IRS Crypto Guidance
In 2014, Notice 2014-21 treated virtual currency as property for tax purposes. It laid the foundation for modern cryptocurrency tax reporting.
Operation Hidden Treasure and Specialized Units
Operation Hidden Treasure focused on hidden ownership and undisclosed taxable virtual currency transactions. IRS materials place it within the Office of Fraud Enforcement. IRS-CI expanded Cyber Crimes Units, building on Liberty Reserve, Silk Road, and BTC-e.
New Digital Asset Reporting Rules
Form 1099-DA supports cryptocurrency tax reporting for broker transactions. Brokers report gross proceeds after 2025, while basis reporting applies to certain covered securities after 2025.
For 2026, the IRS requires gross-proceeds and covered-security basis reporting under the phased rules. Accurate cryptocurrency tax reporting remains the taxpayer’s duty.
How the IRS Tracks Cryptocurrency Transactions
The IRS can connect blockchain records with tax returns, exchange data, wallets, and financial evidence. Those records can identify ownership and tax. Strong cases combine several sources.
Blockchain Analytics Explained
Blockchain analysis is the review of ledger data to trace transfers and address relationships. An address may not name its owner, so investigators need outside evidence.
The IRS confirms third-party analytic tools, supporting blockchain analytics in criminal tax investigations without identifying one required product. This limits claims about specific software.
Blockchain Analysis Tools Used by IRS-CI
IRS-CI confirms third-party blockchain tools. Public IRS sources do not establish a required product. Blockchain analysis IRS methods can combine evidence, while a second blockchain analysis IRS review can test address links and timing.
Exchange Reporting and Third-Party Data
Form 1099-DA gives the IRS broker-reported proceeds and, in some cases, basis. Taxable income remains reportable without the form.
Wallet Tracking and Cross-Chain Analysis
Wallet tracking follows transfers between addresses. Cross-chain review can trace movement when other evidence connects activity. In blockchain analysis of IRS work, investigators can compare that trail with exchange records.
Common Cryptocurrency Tax Violations
Common violations involve unreported taxable activity or intentional efforts to hide income.
- Unreported capital gains: Selling crypto above tax basis can create a taxable gain.
- Hidden offshore wallets: Foreign platforms do not remove U.S. tax duties.
- NFT, DeFi, and staking income: Tax treatment depends on the transaction and IRS guidance.
- Crypto mixing services: Mixing may draw criminal scrutiny when used to conceal proceeds.
- Privacy coins: Privacy features do not create a general tax exemption.
- False cost basis can support a false-return case.
- Whether cryptocurrency transactions can be hidden from the IRS is a key enforcement question because public ledgers preserve records, which can arise in cross-border cases and when ownership evidence exists.
Penalties for Cryptocurrency Tax Fraud
Crypto tax fraud can lead to tax, civil penalties, restitution, fines, prison, and forfeiture. The result depends on intent and evidence.
Civil Penalties
The civil fraud penalty is generally 75% of the underpayment attributable to fraud. Fraudulent failure to file can also reach 75%. A 20% accuracy penalty can apply.
Criminal Tax Prosecution
Tax evasion under §7201 carries up to five years in prison and a $100,000 individual fine. False-return offenses under §7206 can carry up to three years and a $100,000 individual fine. Willful failure to file under §7203 generally carries up to one year and a $25,000 individual fine.
Asset Seizure and Forfeiture
Asset forfeiture can transfer property tied to criminal conduct to the United States. Crypto cases may involve digital assets, money judgments, or related property.
In January 2026, the United States obtained legal title to more than $400 million in assets tied to Helix.
How to Avoid Crypto Tax Problems
Good records and accurate returns reduce the risk of a larger enforcement problem. Every transaction should have a clear tax record.
- Maintain accurate records: Keep dates, units, cost, proceeds, wallet addresses, exchange statements, transfers, and fees.
- File complete tax returns: Report taxable gains, losses, and income even without a broker form. Form 8949 and Schedule D generally report required capital transactions.
- Correct past reporting errors: A mistake does not automatically equal fraud. Review the facts before filing. This distinction matters in civil fraud or criminal tax evasion in crypto cases when intent is disputed.
What to Do If IRS-CI Contacts You
If IRS-CI contacts you, treat it as a legal matter and avoid detailed explanations without advice.
- Get the agent’s name, office, and contact information.
- Preserve wallets, messages, devices, returns, exchange data, and accounting files.
- Do not delete, alter, or create records after the fact.
- Do not guess about basis, ownership, dates, or transfers.
- Ask a qualified crypto tax attorney to review the contact before a detailed statement.
- Counsel can assess whether the matter is civil or criminal.
- An IRS contact does not automatically mean prosecution.
Voluntary Disclosure for Cryptocurrency Tax Issues
The IRS Voluntary Disclosure Practice can help some taxpayers with willful noncompliance seek a resolution before criminal prosecution is recommended. Timing and completeness matter.
- Part I of Form 14457 requests preclearance.
- Part II generally must follow within 45 days after preclearance.
- The practice generally requires that the IRS has not already begun an exam or investigation.
- Disclosure does not guarantee immunity.
- Non-willful errors may call for amended or delinquent returns instead.
- An IRS voluntary disclosure lawyer should assess eligibility before facts reach CI.
The IRS has also proposed changes to the VDP, but the proposal should not be treated as final guidance.
How Verni Tax Law Helps with Cryptocurrency Investigations
Verni Tax Law focuses on IRS disputes, tax fraud, criminal tax matters, offshore disclosure, and federal tax defense. Anthony N. Verni is an attorney, CPA, and MBA. He has 25+ years of tax practice.
- His legal and accounting training connects tax calculations with legal risk.
- His practice includes IRS defense, tax fraud, criminal tax matters, civil litigation, and disclosure work.
- His background helps assess records, reporting gaps, intent, timing, and civil versus criminal risk.
If you need a crypto tax attorney, Verni Tax Law can assess the facts before federal investigators receive more information. Anthony can help organize the tax and legal issues and shape the response.
An IRS voluntary disclosure lawyer can also assess whether a disclosure route fits the facts. For crypto tax exposure, contact Verni Tax Law for a confidential consultation.
Conclusion
IRS-CI’s crypto role shows that digital assets carry federal tax duties. IRS crypto enforcement now combines broker reporting, criminal investigation, DOJ prosecution, and forfeiture. Accurate cryptocurrency tax reporting matters most when records contain unreported income or possible willfulness.
Verni Tax Law is a strong choice for crypto tax exposure because Anthony N. Verni combines attorney, CPA, and MBA credentials with 25+ years of tax practice. His work includes IRS defense, tax fraud, criminal matters, and disclosure. Contact Verni Tax Law to discuss your IRS cryptocurrency investigation.
FAQs
How does the IRS track cryptocurrency transactions?
IRS cryptocurrency investigation work can combine blockchain records, broker reports, exchange records, summons responses, and financial evidence. That evidence also addresses whether cryptocurrency transactions can be hidden from the IRS.
What is IRS-CI’s role in cryptocurrency enforcement?
IRS-CI investigates criminal tax and related financial crimes. An IRS cryptocurrency investigation can involve hidden income, false returns, money laundering, and asset tracing. This reflects IRS enforcement of digital assets.
What triggers an IRS cryptocurrency investigation?
Common triggers include unreported gains, false returns, wallet activity, third-party mismatches, and evidence suggesting willful tax evasion. Large unexplained transfers can also increase attention.
What are the current cryptocurrency tax reporting requirements?
For 2026, taxpayers must report taxable digital asset income, gains, and losses, while brokers report qualifying transactions on Form 1099-DA.
Can blockchain analytics identify crypto tax evasion?
Yes. Blockchain analysis IRS work can trace transactions, while blockchain analytics in criminal tax investigations can connect activity with other evidence.
What penalties apply to cryptocurrency tax fraud?
A 75% civil fraud penalty can apply to fraudulent underpayments, while tax evasion can carry up to five years in prison.
What is the difference between an IRS crypto audit and a criminal investigation?
A civil audit determines tax liability; an IRS-CI investigation examines possible crimes and may lead to DOJ prosecution under the DOJ crypto enforcement strategy.
Can voluntary disclosure reduce criminal tax exposure?
Yes. A timely, truthful, complete disclosure may reduce criminal exposure, but the IRS does not guarantee immunity. It targets willful violations, not simple mistakes.
When should I contact a crypto tax attorney?
Contact a crypto tax attorney before detailed discussions with IRS-CI when records show unreported income, false returns, or possible willful conduct.
How can a criminal tax defense attorney help during an IRS crypto investigation?
A crypto tax attorney can assess exposure, organize records, and evaluate disclosure or defense options before any detailed IRS-CI contact.